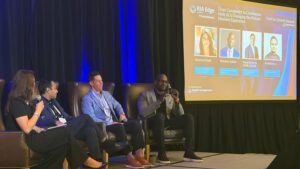
The market for mergers and acquisitions among registered investment advisors has shifted in the past few years, as a wave of new capital—including private equity firms and sovereign wealth funds—has flooded into the space, according to dealmakers who spoke recently spoke at the RIA Edge Austin conference.
But while the pace of acquisitions and deals remains high, with one panelist suggesting there will be 1,000 deals this year among 18,000 RIAs, the reasons for participating in the market have evolved. Many buyers are looking for organic growth engines or specialized skills, just as successful sellers are looking not for a career exit, but for their own growth capital, succession plans and operational support.
“Two years ago, I would have sat up here and said M&A consolidation in our space, we’re still very much in the early innings,” said Frank Guiliano, head of corporate development at Caprock. “I think as we sit here today, it’s not the craziest thing to say we’re starting the middle innings.”
While buyers once prioritized scale, today growth and talent capabilities drive valuations, he said. “That’s become king.”
Despite record deal activity, panelists emphasized that disciplined buyers are turning down more opportunities.
“I’ve said no more in the last two months than I have in the last five years of being in my seat,” said Kevin Corbett, managing director at Mariner Wealth Advisors. “We’re just seeing so much opportunity out there right now. You just have to be selective.”
Corbett said successful integration and organic growth support—not simply capital—separate serious acquirers from opportunistic ones.
“Anybody can write a check,” he said, “but not everybody can successfully integrate a business, nor can everybody help fuel organic growth.”
Guiliano said his firm now digs deeper into organic growth metrics, examining where referrals originate and whether growth is concentrated with one aging advisor or spread across the team.
“It really is a talent business,” he said.
Dustin Mangone, director of Investment Advisor Services at PPC Loan, offered a lender’s perspective, noting a major shift toward internal succession financing.
“If you’d go back to 2013 leading up to 2020, internal succession loans were fairly limited,” he said. “It’s probably now 40% of our annual loan volume.”
He warned that firms failing to equitize junior advisors are exposing themselves to breakaway risk, as next-generation advisors increasingly explore buying out client books from their firms and launching their own shops.
“There’s an immediate arbitrage for that junior advisor,” Mangone said, citing valuations that make breaking away financially attractive when equity promises from senior principals at a firm go unfulfilled.
Corbett called early equity compensation “a very healthy pathway” for retaining talent through a long-term transaction.
“The last thing you want to do is be that sole owner-operator holding 100% of the equity,” if you want to grow the business, he said.
Derek Bruton, head of M&A for Modern Wealth Management, agreed that giving younger advisors equity is key to keeping them. Plenty of firms will create ownership paths for them, or they’ll leave and start their own firm.
“It’s not going to be growth that’s going to be hard in the future,” he said. “It should be retention.”
Mangone said PPC Loan’s underwriting remains grounded in cash flow fundamentals rather than market valuations.
“There’s so much talk around valuation, but we’re really focused more on cash flow,” he said. “At the end of the day, what really pays us back is the credit quality of our borrowers.”
He said the firm is approaching $1 billion in loans “without a default, and arguably no missed payments” over nearly 13 years, attributing historical defaults to personal character issues rather than business performance.
Panelists raised the notion that shifting tax policy following the recent midterm elections may accelerate deal activity and timelines, as sellers seek to lock in capital gains treatment before any changes take effect.
As for the public markets as a source of funding, independent wealth management firms have, for the most part, not participated, largely because they are small firms that don’t want to grapple with the scrutiny and reporting requirements that accompany public trading.
Yet there are firms that have reached the point where going public makes sense. Corbett speculated that IPO “murmurs” among wealth management aggregators could become “whispers” within two years.
But one thing firms cannot do, if they have any consideration for their own future or that of their clients and employees, is stand still.
Bruton mentioned an advisor he knew who considered himself the “Usain Bolt” of wealth management, referring to the Jamaican sprinter and eight-time gold-medal Olympian, and felt no partnership or deal with another firm would be helpful to him. But even Usain Bolt will lose a race if he doesn’t participate, Bruton said.
“You’re going to start losing clients if you don’t keep up with the game. And that’s why a lot of firms have to make that decision. Do I invest in my business and go after it, or do I hitch my wagon to somebody who’s already done that?”